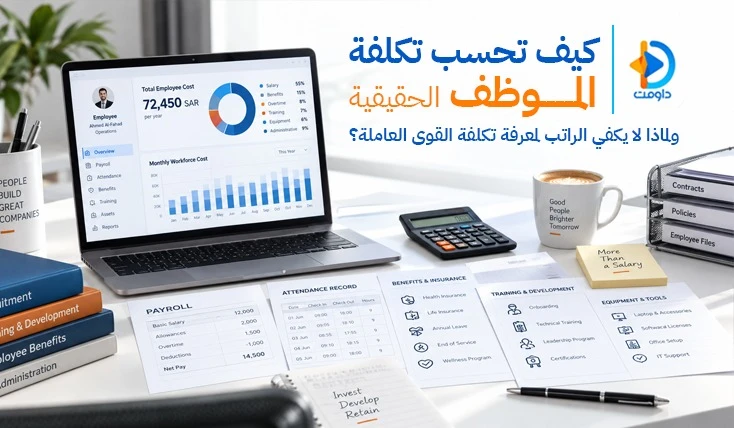
A company may view an employee’s salary as the primary cost it pays in exchange for their work. However, the actual cost of an employee does not stop at the figure stated in the employment contract or the amount shown on the payroll. There are several costs and expenses associated with employing and operating an employee. As departments, projects, and working hours vary, the actual cost may differ from one employee to another even when their salaries are similar. This is why cost management and analysis has become an important tool for companies that want to understand workforce spending more accurately.
In companies with a large number of employees or multiple departments, branches, and projects, knowing the total payroll is not enough to understand where the workforce budget is being spent. Management needs to know the cost of each employee to the company, how that cost is distributed across departments and projects, the cost of actual working hours, and which cost centers are responsible for the largest share of expenses.
This is where the focus shifts from asking, “How much does the employee earn?” to a more accurate question: “What is the employee’s actual cost to the company?”
The cost of an employee is the total amount of expenses a company incurs in connection with that employee over a specific period. It is not limited to the basic salary or the monthly gross salary.
Depending on the nature of the company and its policies, this may include salary, allowances, benefits, operational costs associated with the employee, and other expenses determined by the employee’s role, workplace, and operating model.
Therefore, calculating employee cost requires collecting the financial and operational data associated with the employee rather than relying on salary alone.
For example, a company may have an employee who earns a monthly salary of SAR 10,000. However, when the cost is analyzed more broadly, additional expenses may appear, such as insurance, allowances, operating costs, project-related expenses, and other costs that vary from one company to another.
Therefore, the final figure management needs to understand is not necessarily the employee’s salary, but the actual workforce cost during the relevant period.
Relying on salary alone gives management only a partial view of spending.
If a company has 100 employees with an average salary of SAR 10,000, it may appear that total monthly salaries amount to SAR 1 million. However, this information alone does not answer important questions:
What is the cost of employees in each department?
How much does the workforce cost for a specific project?
What is the actual cost of working hours?
Are some departments carrying higher costs than others?
Is employee cost increasing because of overtime?
What are the variable costs associated with the workforce?
Does the annual workforce budget match actual spending?
For this reason, companies need to analyze employee costs rather than simply reviewing payroll records.
Companies can use Dawmt Payroll Management to understand salaries and employee entitlements, while cost analysis requires looking at the broader picture of employee-related spending.
There is no single fixed value that applies to every company when calculating employee cost. Costs vary depending on the industry, company size, job roles, projects, and company policies.
However, employee costs can generally be divided into several main categories.
Salary is the starting point for calculating employee cost, but it is not necessarily the final figure.
Management needs to understand the employee’s basic salary and the financial components associated with it according to the company’s compensation structure.
Employee cost may include different allowances and benefits depending on the employee’s role and company policies.
When analyzing workforce costs, it is important not to treat all employees as having the same operating cost, because the value of benefits and other associated expenses may vary between roles.
A company may incur operating costs associated with an employee, such as health insurance, uniforms, and certain fees and other expenses depending on the nature of the business.
Dawmt’s Cost Management and Analysis service allows companies to add and categorize employee operating costs, including examples such as visas, health insurance, uniforms, and taxes, and then associate these costs with employees for more organized analysis.
Overtime can have a significant impact on an employee’s cost to the company, especially when overtime hours continue over long periods.
An employee with a fixed salary who consistently works additional hours may have a higher operating cost than another employee with the same salary who works within planned working hours.
Therefore, companies should consider the cost of actual working hours rather than looking only at the monthly salary.
For project-based companies, knowing the individual cost of an employee is not enough.
It is also important to know how much of the employee’s cost is allocated to each project.
If an employee spends 50% of their time on one project and 50% on another, allocating their cost accordingly helps management understand the actual cost of each project more accurately.
A simplified approach can be represented by the following formula:
This is not a standardized accounting formula for every company, but rather a practical way to understand the concept.
For example, assume an employee receives a salary and benefits worth SAR 12,000 per month, with additional employee-related costs of SAR 1,500 and variable costs allocated to the employee amounting to SAR 500.
In this example:
The employee’s salary alone was SAR 12,000, while the employee’s cost under the assumptions in this example becomes SAR 14,000.
The purpose of this example is not to establish a fixed cost for every employee, but to demonstrate the difference between salary and the broader employee cost that management needs to analyze.
Knowing the company’s total workforce cost is important, but understanding how that cost is distributed is even more valuable when making decisions.
Suppose a company has:
Sales Department
Human Resources Department
Operations Department
IT Department
Customer Service Department
If management only knows that the total employee cost is SAR 2 million per month, it may not have a clear understanding of what is driving that figure.
However, when employee costs are distributed by department, management may discover that one department accounts for a significant portion of the cost while another operates at a lower cost.
This is where meaningful analysis begins.
A higher employee cost in a particular department does not necessarily mean that the department is inefficient. The department may be responsible for larger operations, employ specialized professionals, or work on high-value projects.
Therefore, costs should be compared with workload, results, working hours, and productivity rather than evaluating a department based on cost alone.
Cost centers are a way of organizing expenses and assigning them to the department, branch, activity, or business unit responsible for those costs.
Instead of having all employee costs appear as one overall figure, a company can divide them into different cost centers based on its organizational and operational structure.
A cost center may be:
A department.
A branch.
A project.
An operational activity.
A business unit.
Cost centers become increasingly important as a company grows, operates multiple branches, or manages several projects simultaneously.
For example, if a company has three projects, it is important to know how much human resources each project consumes, how many working hours are involved, and what the employee cost is for each project.
This allows management to understand costs more realistically.
For project-based companies, one of the biggest mistakes is treating employee salaries as general costs that cannot be allocated.
An employee may work on one project or several projects during the month. Therefore, allocating their cost according to working hours or the company’s approved allocation method helps determine the actual cost of each project.
This makes employee cost by project an important indicator for both financial and operational management.
If a particular project requires significantly more working hours than originally planned, its cost may increase even if employee salaries remain unchanged.
If the company does not track working hours and project allocation, the project cost may appear lower or higher than it actually is.
Through Dawmt’s project management and tracking capabilities, companies can analyze the number of employees participating in a project, actual working hours, human resource costs used, and the allocation of human resource costs across projects.
You can explore Dawmt Project Management and Tracking to better understand the relationship between resource allocation, working hours, and human resource costs.
A company may have an employee with a specific monthly cost, but an important question is sometimes:
This metric becomes particularly important when a company works on projects or provides services priced according to effort and time.
In a simplified form, the cost per working hour can be estimated as:
For example, if an employee’s monthly cost is SAR 15,000 and the employee works 150 actual hours during the month:
This is a simplified example and does not necessarily represent the accounting method used by every company. However, it demonstrates the importance of connecting employee cost to actual working hours.
This is where operational data becomes valuable, because hourly cost cannot be properly analyzed if the company does not have accurate working-hour data.
Attendance and time tracking may appear unrelated to financial analysis, but they are actually important sources of operational data.
Actual working hours, lateness, absence, overtime, and shifts are all data points that can affect workforce cost analysis.
If a company analyzes employee cost without knowing actual working hours, it may be missing an important part of the overall picture.
Companies can use Dawmt’s Attendance Management System to monitor attendance and working hours and analyze working time more accurately.
When time data is integrated with payroll and cost data, management has a stronger foundation for analyzing workforce costs.
No.
This is one of the most important points to consider when analyzing employee cost.
A high-cost employee or department does not automatically indicate a performance problem.
An employee may be highly specialized and work on high-value projects. A department may have higher costs because its work requires specialized skills or because it is responsible for large-scale operations.
Therefore, the purpose of employee cost analysis should not simply be to identify the “most expensive” employee.
A better analysis connects:
This enables management to distinguish between high costs that are operationally justified and high costs that require further review.
When costs are recorded as a total amount, it can be difficult to identify the source of an increase.
However, by using cost centers, companies can compare expenses across departments, projects, and branches.
For example, if the company’s workforce cost increases by a certain percentage during a month, management can review:
Which cost center experienced an increase in expenses?
Was the increase caused by the number of employees?
Was it caused by increased working hours?
Is there recurring overtime?
Is there a new project?
Have any cost items changed?
Is the increase temporary or ongoing?
In this way, cost data becomes more than just financial figures; it becomes a tool that helps management understand what is happening within the company.
A realistic workforce budget cannot be built based on current salaries alone.
Management needs to consider potential changes in headcount, variable costs, new projects, business expansion, and changing departmental requirements.
Therefore, employee cost analysis helps build a more realistic picture when planning the budget.
Dawmt’s Cost Management and Analysis service enables companies to monitor the annual budget on a monthly basis, control variable costs, and link expenses to cost centers and projects.
This type of analysis helps management compare planned costs with actual spending instead of waiting until the end of the year to discover a significant variance in expenses.
One common mistake is treating all employees in the same way.
However, employee cost can vary based on:
Job title.
Department.
Work location.
Contract type.
Number of working hours.
Project assignment.
Job-related costs.
Overtime.
Benefits and operating costs.
Therefore, average employee cost may be useful for general planning, but it does not replace detailed analysis when management needs to make a decision regarding a specific department or project.
Manual analysis becomes more difficult as the number of employees increases and departments and projects become more complex.
Management may need to collect data from:
Employee records.
Payroll.
Attendance and time tracking.
Projects.
Departments.
Cost centers.
Expenses.
Working hours.
The company then needs to connect these datasets to determine the actual cost of an employee.
This is where integrated systems become valuable.
Instead of having data distributed across multiple files and systems, operational and financial data can be connected within one system, allowing management to use reports and analytics to review results.
Dawmt provides Cost Management and Analysis as part of its human resources management ecosystem. The service focuses on giving companies financial visibility into HR data, analyzing expenses, and connecting them to cost centers and projects.
The service includes several functions that help build a clearer picture of workforce costs, including:
Adding and categorizing employee operating cost items.
Linking employee costs to specific cost centers.
Linking costs to projects.
Calculating monthly employee-related expenses.
Generating reports that connect actual working hours with cost.
Monitoring the annual budget on a monthly basis.
Controlling variable costs.
The platform also provides reports on hourly cost and productivity, helping companies move beyond simply knowing total expenses and understand the relationship between time, cost, and human resources.
You can also explore Dawmt’s Reports and Analytics to learn how HR data can be transformed into reports that help management monitor key indicators and make informed decisions.
The goal of employee cost analysis is not to reduce costs at any expense.
Reducing workforce costs without considering productivity can lead to the opposite result.
If a company randomly reduces its workforce, overtime may increase, projects may be delayed, and pressure on existing teams may rise. As a result, the company may not achieve the expected savings.
A better approach is to understand the relationship between cost and results.
If a particular team has high costs, ask:
What are we getting in return for this cost?
Are they completing more projects?
Are they working on high-value projects?
Are working hours being allocated effectively?
Are there unused working hours?
Is there overtime that could be reduced?
Does the company need to redistribute resources?
These questions turn employee cost analysis into a decision-making tool rather than simply a financial report.
Management can monitor several key metrics, such as:
Used to compare workforce costs across different periods.
Shows the cost carried by each department, while ensuring that cost is evaluated alongside workload and results.
An important metric for project-based companies because it helps determine the human resource cost associated with each project.
Helps understand the relationship between employee cost and actual working hours.
Helps identify differences between planned spending and actual expenses.
This gives the company only part of the cost picture and leaves out other expenses.
Having one large overall figure does not help identify the source of the problem.
An employee’s overall cost may be reasonable, but the cost per working hour may be high due to fewer actual working hours or poor resource allocation.
This makes it difficult to determine the profitability of projects that rely on human resources.
Analyzing costs only once a year is not enough for companies where projects, headcount, and expenses change continuously.
Cost should be evaluated alongside productivity, results, and workload rather than in isolation.
Start by identifying all the cost items the company wants to include in employee cost calculations.
Then define the cost centers, departments, and projects that need to be monitored.
Next, link each cost to the appropriate employee, department, or project according to the company’s policies.
The company should then collect actual working-hour data and compare it with costs.
Finally, use periodic reports to compare results across months and identify trends.
This approach turns employee cost calculation into an ongoing process rather than a calculation performed only during budget preparation.
It is important to treat employee cost as a value that can change over time.
Costs may change due to:
Increased working hours.
Overtime.
Moving an employee to another project.
Department changes.
Changes in benefits.
Addition of new cost items.
Changes in project allocation.
Increases or decreases in workload.
Companies that monitor costs regularly can identify these changes early instead of discovering them after they have already affected the budget.
Knowing an employee’s salary is important, but it is not enough to understand workforce costs.
The true cost of an employee requires analyzing a broader set of data, including compensation, employee-related costs, working hours, projects, departments, cost centers, and variable expenses.
Employee cost should also not be viewed simply as a number used by management to compare employees. It should be treated as an indicator that helps management understand how human resources are being used and where the workforce budget is going.
By analyzing employee costs and connecting them to cost centers and projects, companies can gain clearer visibility into spending, compare budgeted costs with actual costs, analyze the cost of working hours, and make more informed decisions about resource allocation.
Through its Cost Management and Analysis service, Dawmt provides tools that help companies organize employee cost items, link them to cost centers and projects, monitor monthly and variable costs and budgets, and analyze working-hour costs.
If a company wants to move from simply knowing “How much do we pay our employees?” to understanding “How much does our workforce actually cost, and where is that cost going?”, cost analysis is an essential step toward building clearer financial and operational visibility.
Employee cost is the total expenses a company incurs as a result of employing and operating with an employee over a specific period. It is not necessarily limited to salary, but may include other costs and expenses depending on the company’s structure and policies. Cost management and analysis can help track employee cost items more accurately.
Employee cost can be calculated simply by adding wages, direct costs, employee-related costs, and allocable operating costs, then analyzing them based on the relevant period, department, or project when needed.
Knowing the cost of an employee helps companies build more accurate budgets, analyze the cost of departments and projects, understand workforce spending, and make better decisions about resource allocation. Cost management and analysis also helps companies track these expenses in a more organized way.
A practical guide to annual leave planning that balances employee time off with operational needs, helping HR teams anticipate staffing gaps and organize coverage before peak periods.
Learn about the causes of accumulated leave balances and how effective leave management can improve workforce planning and reduce operational challenges.
Learn about the key challenges of external workforce management and how accurate data helps monitor attendance, locations, payments, and contractor performance while improving operational efficiency.